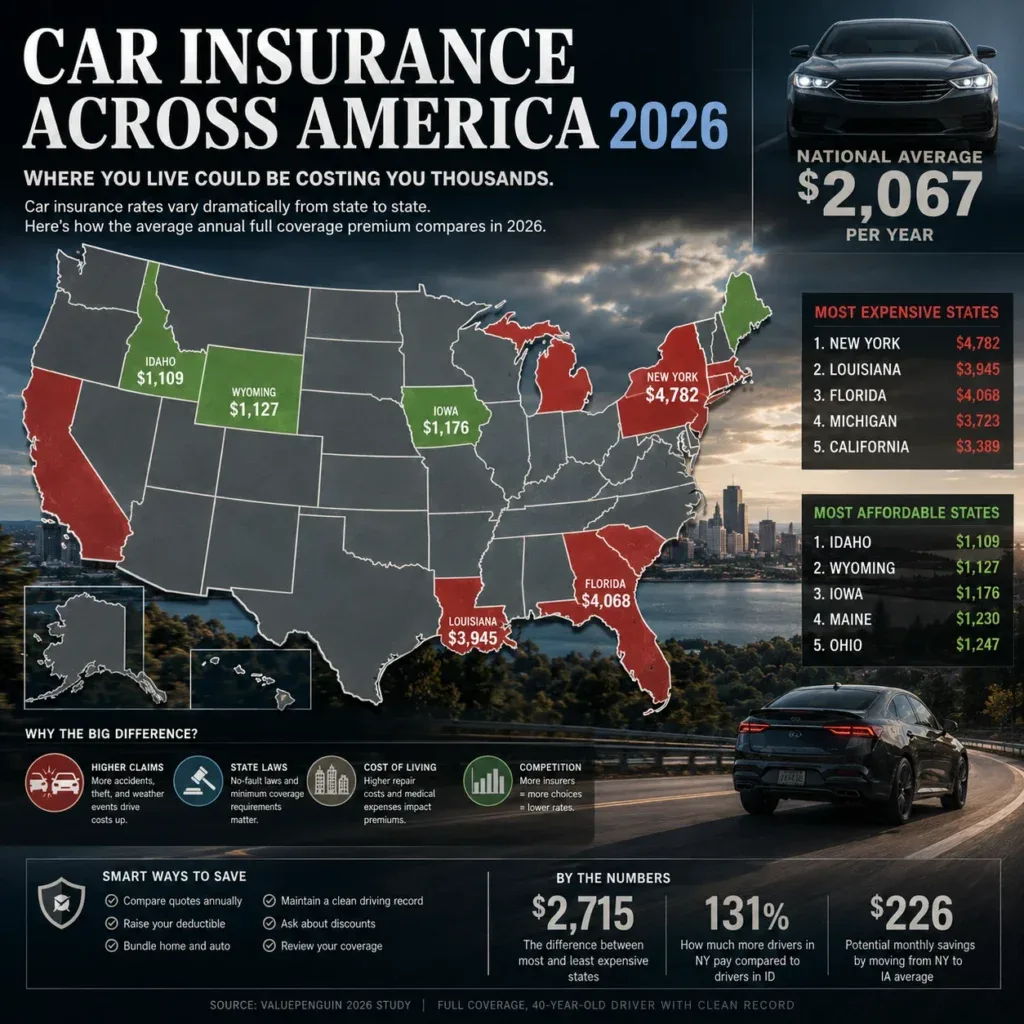
National premiums are not crashing. Insurify still sees 2026 finishing up about 1% after last year’s dip.
Some nameplates did crash — on purpose. Compare.com’s late-summer cut of 2025–2026 models found ten vehicles down 15% or more year over year. Five of them are the ones worth shopping before a fall renewal or a new-car pencil.
These are averages. Your ZIP and your record still write the check.
1. Hyundai Ioniq 5 — minus 19%, about $704, to $2,990
Biggest percentage drop on the list. IIHS Top Safety Pick+. Battery and repair costs finally showed up in the rate files after years of “EV surcharge” folklore. 2026 SE money starts near $35,000. If you already own one and last year’s premium looked like a Tesla, get a new quote. The book moved.
2. Nissan Leaf — minus 18%, about $687, to $3,096
New Leaf is a small crossover, not the old hatch. Insurers treat it like a cheap EV with a known parts bin. $29,990 start. Still not Buick Envista cheap. Still $700 off last year’s average.
3. Dodge Charger — minus 18%, about $917, to $4,146
Largest dollar cut. Still expensive. Muscle-car and EV Charger share a name and a claims history that finally cooled a notch. $917 is real. $4,146 a year is still a second compact-car payment. Do not buy a Charger because insurance got nicer. Buy it because you wanted the car. Then shop the savings.
4. Subaru Impreza — minus 18%, about $509, to $2,392
This is the one that actually looks cheap after the cut. Small, AWD, boring in the best way. If you are renewing an Impreza at last year’s number, you are donating.
5. Toyota Sequoia — minus 17%, about $561, to $2,714
Full-size hybrid hauler. Family-vehicle rating plus a year of claims data. Highlander was right behind it at the same 17%. Body-on-frame money with a midsize-SUV insurance vibe is the surprise.
How to Claim It
The carrier will not mail you a coupon that says “Ioniq 5 file updated.”
Call before auto-renew. Ask for a requote on the same VIN. Then get two outside quotes with identical limits and deductibles. If you financed the car, you still need full coverage — the drop is on that stack, not a switch to liability-only.
Safety discounts and IIHS badges only work if they are on the policy. New-car and anti-theft boxes too. A 19% model-level cut plus a missed discount is how people leave $900 on the table.
Would you requote an Ioniq 5 before the card is charged — or let last year’s EV scare price ride into fall?
Related: Car Ownership Cost Calculator