September is when a lot of policies auto-renew while you are at a cookout.
The national story is small. Insurify says full-coverage premiums fell about 6% in 2025, then started climbing again. Their mid-year read: 27 states up in the first half of 2026, 32 states on track to finish the year higher, national average ending near $2,242 — roughly a 1% year-over-year bump.
Your mailbox does not care about a 1% national average. It cares about five real shifts.
1. Connecticut is the expensive surprise
Insurify put Connecticut at the top of the 2026 climb — about 10% more for full coverage in the first half, an extra $251 a year versus six months earlier, and a path toward 15% for the full year. That is not a $4 surcharge. That is a second streaming bill.
Repair costs and claim severity are the usual suspects. If your renewal is this month and the number jumped without a ticket, you are not imagining it.
2. Kentucky and West Virginia joined the “now above average” club
Same report: Kentucky and West Virginia on track for about 8% higher by year-end. Kentucky’s average flipped from below the national number to above it. Illinois and Nevada sit in the plus-6% pack.
These are not Florida-crisis headlines. They are quiet filings that show up as $120–$200 at renewal and get blamed on “the market.”
3. New York actually got cheaper — and the rules tighten again this fall
First-half 2026 cut New York full-coverage averages about 5% in Insurify’s book. Some year-over-year reads showed a much bigger drop from the 2025 peak — hundreds of dollars for a typical full-coverage policy — enough to knock the state down the “most expensive” list without making it cheap.
New York DFS also told insurers that starting November 27 they lose the old flex-rating shortcut for increases up to 5%. Rate hikes need the superintendent first. Decreases can still flow. If you renew in September you are still on the current book. The next cycle is a different filing world.
4. Florida is no longer only a horror story
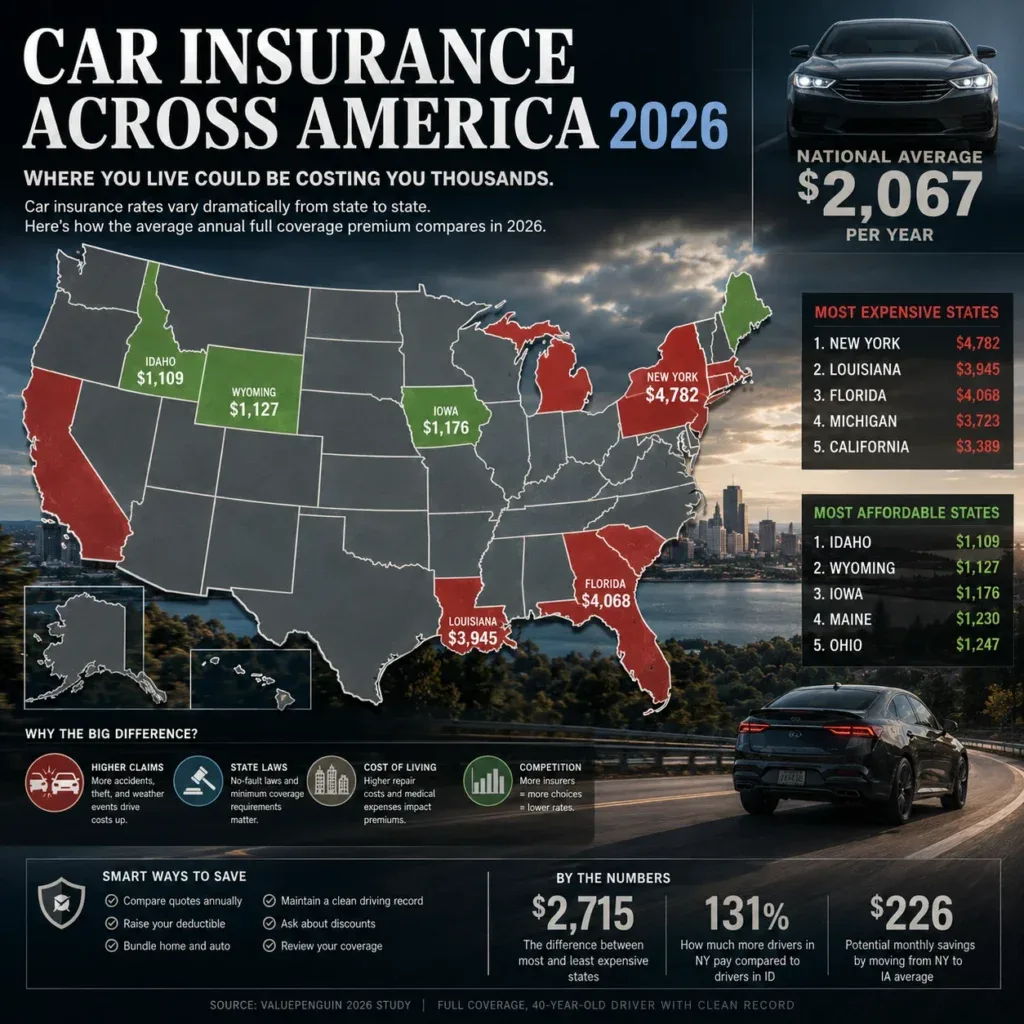
Florida is still one of the most expensive states on almost every ranking — mid-$3,000s in some 2026 averages. The change is direction. After years of double-digit pain, several 2025–2026 snapshots showed Florida among the largest declines, including broker data that put monthly premiums down nearly 20% in one book.
That does not mean your Allstate bill looks like Vermont. It means the worst of the spiral paused. Shop anyway. A 19% drop in a statewide average can still leave your ZIP expensive.
5. The split market: D.C. and New Jersey down, Maryland and Oregon still climbing
Washington, D.C. posted one of the sharpest first-half drops (about 7% in Insurify’s set) while remaining brutally expensive in dollars — high $3,000s. New Jersey showed a first-half decline after a brutal 2025 jump in other datasets.
Zebra’s 2026 state work still flagged New Jersey and Oregon among the bigger year-to-date increases depending on the window you measure. Maryland and Utah showed up on projection lists for further second-half pressure. Two reports can disagree on the same state because they sample different carriers and months. Your declarations page is the only number that cashes.
What to do before auto-renew hits
Four numbers: premium versus last year, deductible, mileage the company thinks you drive, and whether comprehensive still matches the car you actually park. Then get two outside quotes. A 6% “market” move is not a reason to stay loyal.
Is your September renewal cheaper than last fall — or did your state quietly join Connecticut?
Related: Car Ownership Cost Calculator