September mail is not junk.
Most six- and twelve-month policies spit a renewal packet 30 to 60 days out. Some states force extra notice if the hike is ugly — Wisconsin wants 60 days when the increase tops 25% and nothing about you changed. The packet looks boring. That is the point. Auto-renew is how carriers keep the book without a conversation.
Do these five things before the charge hits.
1. Read the new premium against last year’s — not against “the market”
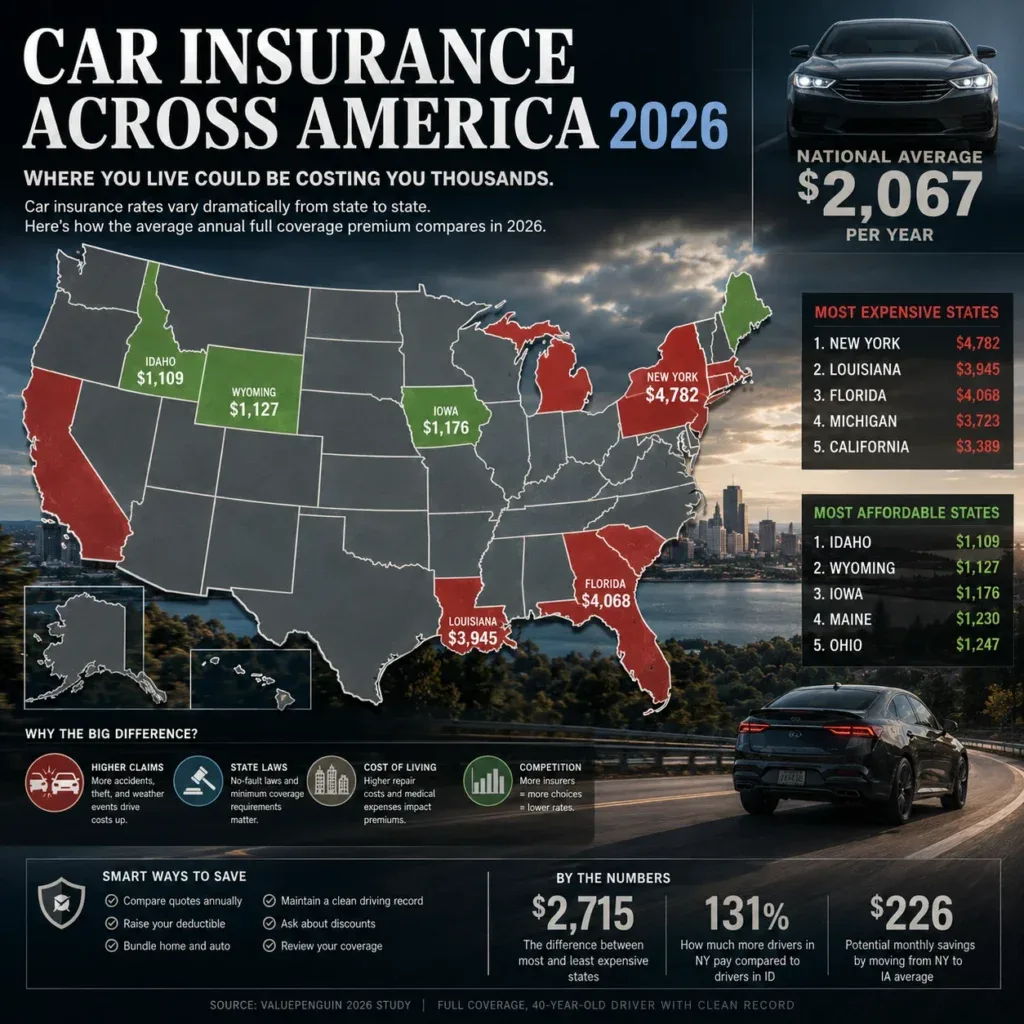
Insurify put 2026 on track for a small national bump after a 6% drop in 2025. Your ZIP is not the nation. Connecticut and Kentucky climbed. New York and parts of Florida gave some back. The only number that matters is your declarations page versus the one in the drawer.
If the premium jumped and you did not add a teen, a ticket, or a Tahoe, ask why in writing. Filing changes, territory factors, and “loss cost” are the usual fog. Fog is not a reason to stay.
2. Fix the mileage they think you drive
Work-from-home three days and a 12,000-mile rating is free money for them. A kid in college and the car sitting is the same leak the other way.
Call and correct annual miles before the term locks. Usage is a rating factor. The app that tracked you last year may still think you commute I-95.
3. Re-price the deductible before you strip coverage
$500 to $1,000 is the first clean cut. It is not the same as dropping comprehensive and collision.
Lenders still require full coverage on a financed or leased car. Cash buyers on a $6,000 Civic can talk liability-only. Cash buyers on a $22,000 hybrid should not. The 10% rule still works: if comp-plus-collision is 10% of actual cash value, the coverage is eating the asset. Raise the deductible first. Then do the math.
4. Audit the people and the cars on the page
A sold Civic still listed is a claim argument waiting. A roommate who moved out is a rating ghost. A newly licensed 17-year-old not listed is a denial letter.
Fall is when households change — school, leases, the used Civic that became a campus car. The policy does not update itself. Wrong VIN and wrong operator are how good claims go bad.
5. Get two quotes that are not your current company
Loyalty is priced in. Comparison sites are a start. A direct quote from a second and third carrier is the actual test. Match limits. Match deductibles. Match the cars. A cheaper quote with 25/50/25 is not cheaper. It is a different product.
If you bundle home and auto, unbundle the quote once so you can see what the car actually costs. Then decide if the bundle discount is real.
Non-renewal letters are a different animal. Those often come 30–75 days out. Read the reason. Shop the same week. A lapse is more expensive than a bad renewal.
Would you let the same carrier charge the card again — or is this the fall you finally opened two tabs?
Related: Car Ownership Cost Calculator